Have you ever saved every money saving tips post on Pinterest, started strong on the first of the month, and then quietly given up by the fifteenth?
Same. For years my saving plans had the lifespan of a New Year’s resolution. I would open a new savings account, name it something cute like “Paris fund,” put money in once, and then pull it back out two weeks later for something I cannot even remember now.
I blamed myself. I thought I lacked discipline, that some women are simply wired to be good with money and I was not one of them.
What I was actually missing was a ritual.
The short version
- Most money saving tips fail because they are rules that rely on willpower. Rituals do not.
- A savings ritual has three parts: a trigger (payday), an action (a 20-minute money date) and a reward (the end-of-month transfer).
- A common guideline is the 50/30/20 rule: 50% needs, 30% wants, 20% savings. Start with 5 to 10% if 20% is not realistic yet.
- Build an emergency fund of three to six months of living costs, one month at a time.
- Living paycheck to paycheck? Start tiny, find one spending leak and save half of every windfall.
Why Most Money Saving Tips Never Stick
Most money saving tips are rules. Cancel subscriptions. Stop buying coffee. Use cash only. Track every single expense. They sound reasonable, and they work for about a week.
The problem is that rules rely on willpower, and willpower runs out. Especially on a Friday night after a long week, when your online cart is full and your motivation is empty.
Rituals are different. Nobody brushes their teeth out of discipline. It is simply what happens in the morning. It is part of who you are. That is the energy we want for saving money: less “I have to,” more “this is just my thing now.”
Saving starts with a decision, not a spreadsheet
Being money conscious does not start when you finally make that perfect savings chart. It starts the moment you intentionally decide that saving is part of your life. The chart comes later. The decision comes first, and the ritual is what keeps it alive.
Turn the rule into a ritual
What’s Your Saving Personality?
Four quick questions. Your answer tells you which part of the ritual to focus on first.
How to Make Saving Money a Habit: The Ritual Framework
A savings ritual has three parts. Keep all three small and pretty, and your brain will start looking forward to it.
It happens on its own, regularly, and already comes with emotion.
Twenty minutes with your money, a candle and a matcha.
Moving your leftover into savings at the end of the month.
The trigger: payday
Payday is the most natural trigger you will ever get. Right now that emotion probably says “shopping.” We are going to give it a new meaning.
The action: your money date
On payday, or the evening after, sit down for 20 minutes with your money. Light a candle, make a matcha, put on a playlist. Then do these four things. Tick them off as you go.
The reward: the end-of-month transfer
Here is my personal twist. I do not move my savings on payday. I keep the planned leftover in my account until the end of the month, and then I invest or save it.
It gives me peace of mind. If something unexpected happens during the month, the money is still there, and I do not have to touch my investments or feel like I failed. When my next paycheck arrives, I can freely invest last month’s money, knowing the new month is already covered. That transfer has become the most satisfying moment of my month.
A small honest note: if you know you would spend anything left in your account, flip it around and move a fixed amount on payday instead. The best ritual is the one that matches your personality, not mine.
How Much Money Should I Save Each Month?
This is the most searched question about saving, and the answer is personal. Here is a starting point that many financial experts use.
Put 50% of your take-home pay toward needs, 30% toward wants and 20% toward savings and investing.
Twenty percent is a beautiful goal. It is also not realistic for everyone right now, especially if rent eats half your salary on its own. If that is you, start with 5 or 10 percent. The consistency matters more than the size.
How much should I save from each paycheck?
If you get paid once a month, aim for 10 to 20 percent of each paycheck. If you get paid every two weeks, split the monthly goal so each paycheck carries part of it. And before anything else, build an emergency fund. The usual advice is three to six months of living costs. That sounds huge, so break it down: first one month of rent, then two, then three.
Play with your numbers
Healthy Spending Habits That Make Saving Easier
Saving is only half of the story. The other half is how you spend, because every dollar you spend wisely is a dollar that can land in your savings.
Know your musts and your cans
A must keeps your life running. A can is something lovely you could live without right now. I explain the full must vs. can rule here. Cans are allowed, but only from money that is left after the musts and the savings plan are covered.
Spend more on evergreen, less on seasonal
Pieces you will wear for years, like a great coat, a quality bag or classic knitwear, are worth spending more on. If you will be tired of it by next season, it does not deserve a big part of your budget.
Keep a wishlist instead of a cart
I have a wishlist full of things I would love to own. The difference now is that I do not buy them all at once. Every item waits at least two weeks. If I still want it after that, and I have free money for it, it can come home with me. Most of the time, the urge quietly disappears.
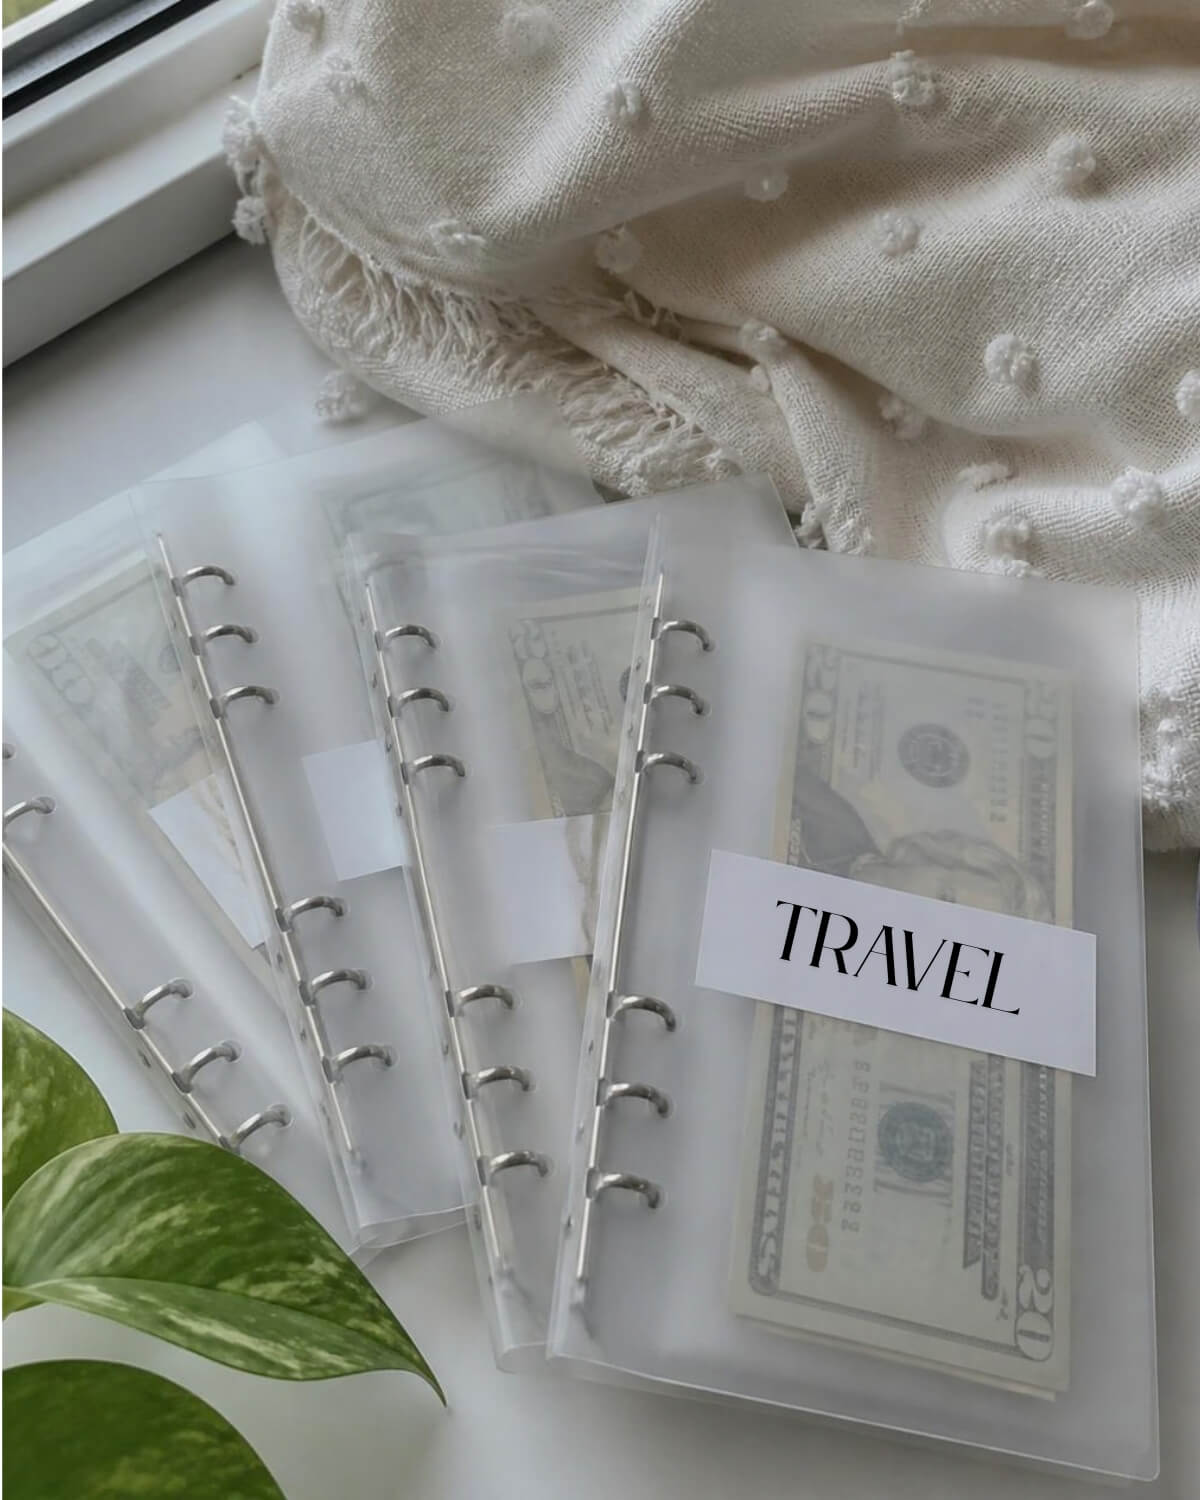
How to Save Money When You Live Paycheck to Paycheck
If there is nothing left at the end of the month, the usual money saving tips can feel almost insulting. So let me keep this real.
Start tiny. Even $10 or $20 a month counts. The goal right now is the habit, not the amount.
Save windfalls. Tax refunds, birthday money, a bonus, money from selling clothes you never wear. Put at least half straight into savings.
Protect your musts first. If your income only covers the basics, your ritual is still valuable. Paying your musts on time and planning the rest carefully keeps you out of debt, and that already counts as progress.
Living paycheck to paycheck does not mean you are bad with money. Often it means your income and costs are tight. A ritual will not magically fix that, but it will show you exactly where you stand, and that clarity is where every change begins.
Find your leak
Look at last month. Which categories surprised you most? Tap them and get one specific fix for each.
Realistic Expectations: The First Three Months
Month one
You will probably forget a money date or spend part of your savings. That is fine. You are learning the rhythm.
Month two
The ritual starts to feel familiar. Payday reminds you of your candle and your matcha, not only of your cart.
Month three
This is usually where it clicks. The end-of-month transfer feels normal, and you protect your savings without needing a rule.
No instant results.
No perfect streak.
Just a small monthly moment that slowly changes how you feel about money.
Is a Savings Ritual for You?
Tick everything that sounds like you.
These are the personal finance tips I wish I had heard years ago, right next to these 15 money habits of a high-value woman. Saving does not need to be a punishment. It can be the most grounding 20 minutes of your month.
Savings Ritual FAQ
How to make saving money a habit?
Tie saving to a trigger that already exists, like payday, and turn it into a small ritual. A 20-minute monthly money date where you pay bills, plan spending and set a savings goal makes saving feel automatic. A satisfying reward, like the end-of-month transfer, helps your brain keep coming back to it.
How much money should I save each month?
A common guideline is the 50/30/20 rule, which puts 20 percent of your take-home pay toward savings and investing. If that is not realistic yet, start with 5 or 10 percent and increase it over time. Consistency matters more than the exact amount.
How much should I save from each paycheck?
Aim for 10 to 20 percent of each paycheck if your budget allows it. If you are paid every two weeks, split your monthly goal across both paychecks. Build an emergency fund of three to six months of living costs before focusing on bigger goals.
How to save money when you live paycheck to paycheck?
Start with a tiny, fixed amount, even $10 or $20 a month, to build the habit. Find the one spending category that surprised you most last month and cut it by half, shop with a grocery list every time and save at least half of any windfall. Paying your necessities on time and avoiding debt already counts as progress.
Should I save on payday or at the end of the month?
Saving on payday works best if you tend to spend whatever is in your account. Saving at the end of the month keeps a cushion available for surprises and lets you invest last month’s leftover once the new paycheck arrives. Pick the version you will actually repeat.
Questions or collaborations: info@opulentfemme.com